
Make a 52-Week Savings Challenge Affordable
Compare a rising weekly savings challenge with a fixed contribution, and choose a version that fits your cash flow instead of a viral calendar.
By Keel · Savings ·
Free 7-day trial. No card required. Subscribe for $4.99/month to continue; no charge unless you subscribe.
Decide what the challenge is for
A savings challenge is a contribution pattern, not a financial product or a guaranteed result. Name the purpose first: a small reserve, a planned expense or another milestone. CFPB savings worksheets connect a target with contributions and a time frame. The pattern should serve that purpose rather than determine whether you are good at money.[1]
Notice the rising commitment
The familiar increasing pattern starts at $1 and adds another dollar to the weekly contribution. Later weeks require much more than early ones, sometimes when holidays or annual bills also arrive. Check the whole schedule before beginning. If your income is unstable, an affordable flat amount or flexible contribution may be easier to maintain.[2]
Compare two equal totals
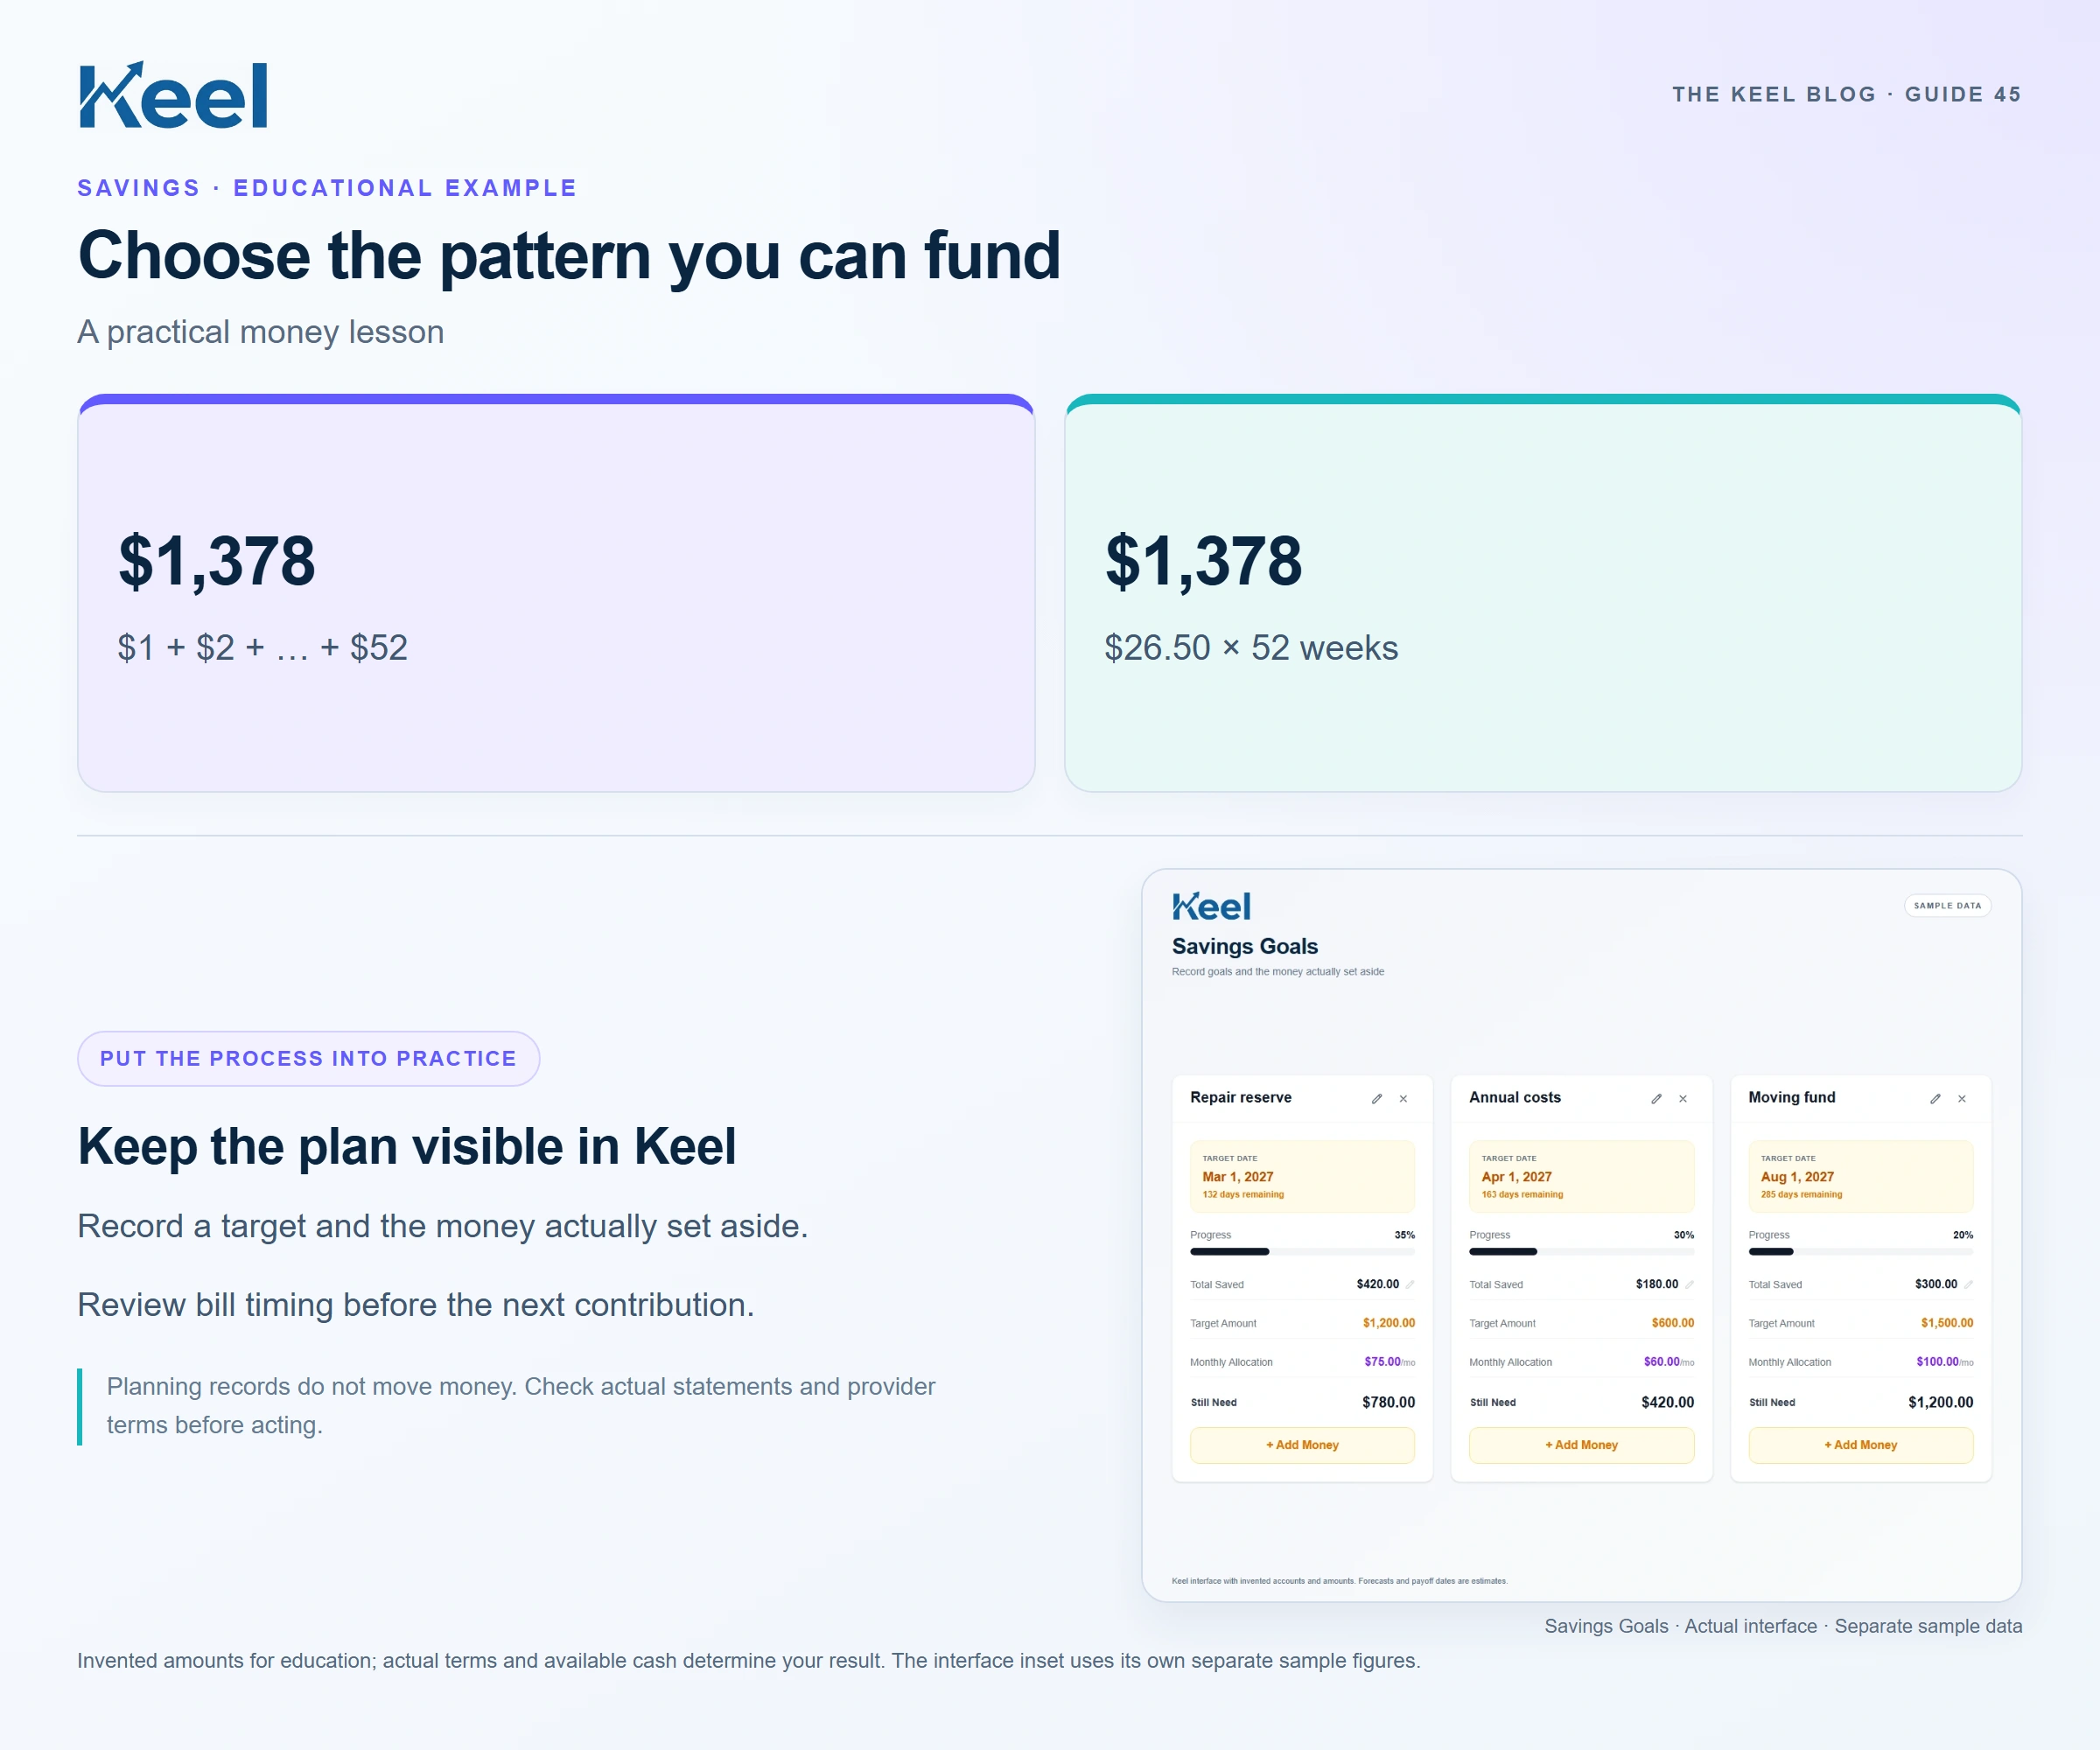
Adding the integers one through fifty-two gives $1,378. Contributing $26.50 for fifty-two weeks produces the same total before interest or withdrawals. The flat version does not promise the same experience or affordability; it simply spreads the arithmetic evenly. Neither total exists until the contributions are actually made.
| Pattern | Total |
|---|---|
| Increasing $1 through $52 | $1,378 |
| 52 × $26.50 | $1,378 |
Track the funded target in Keel
Create a Savings goal for the purpose and record the money actually set aside. Review Bills and the forecast before difficult weeks, especially if the contribution increases. Keel does not automatically execute the fifty-two transfers or provide a built-in challenge schedule. Keep the chosen contribution calendar separately if you need one.
Use a missed week as feedback
If a contribution does not fit, adjust the target date or pattern instead of borrowing to preserve a streak. Record withdrawals honestly and review what changed. The useful outcome is money saved without destabilizing essentials. Completing fewer affordable contributions can support that aim better than finishing a screenshot-friendly challenge with new debt.
Footnotes and sources
U.S. consumer education. Sources checked . General education, not an individual financial or legal recommendation.