
Give Your Final Debt Payment a Next Job
Verify a paid-off account, adjust payment arrangements and redirect the freed monthly amount toward reserves and other goals without losing track of costs.
By Keel · Debt planning ·
Free 7-day trial. No card required. Subscribe for $4.99/month to continue; no charge unless you subscribe.
Confirm what is actually paid off
Check the lender’s final balance and whether more interest, fees or adjustments will appear. Keep the final confirmation and verify automatic-payment settings. A monthly bill marked paid is not proof that a loan is cleared. Do not close or change an account merely to make the dashboard look complete without understanding the provider’s process.
Choose the next priority
Emergency reserves, predictable future costs and other financial goals still need funding after a debt ends. The CFPB’s savings guidance starts with a realistic purpose and contribution plan. Reconsider what risks remain rather than immediately filling the freed payment with another installment purchase. The new flexibility is useful even if it first repairs a depleted reserve.[1] [2]
Allocate an invented freed payment
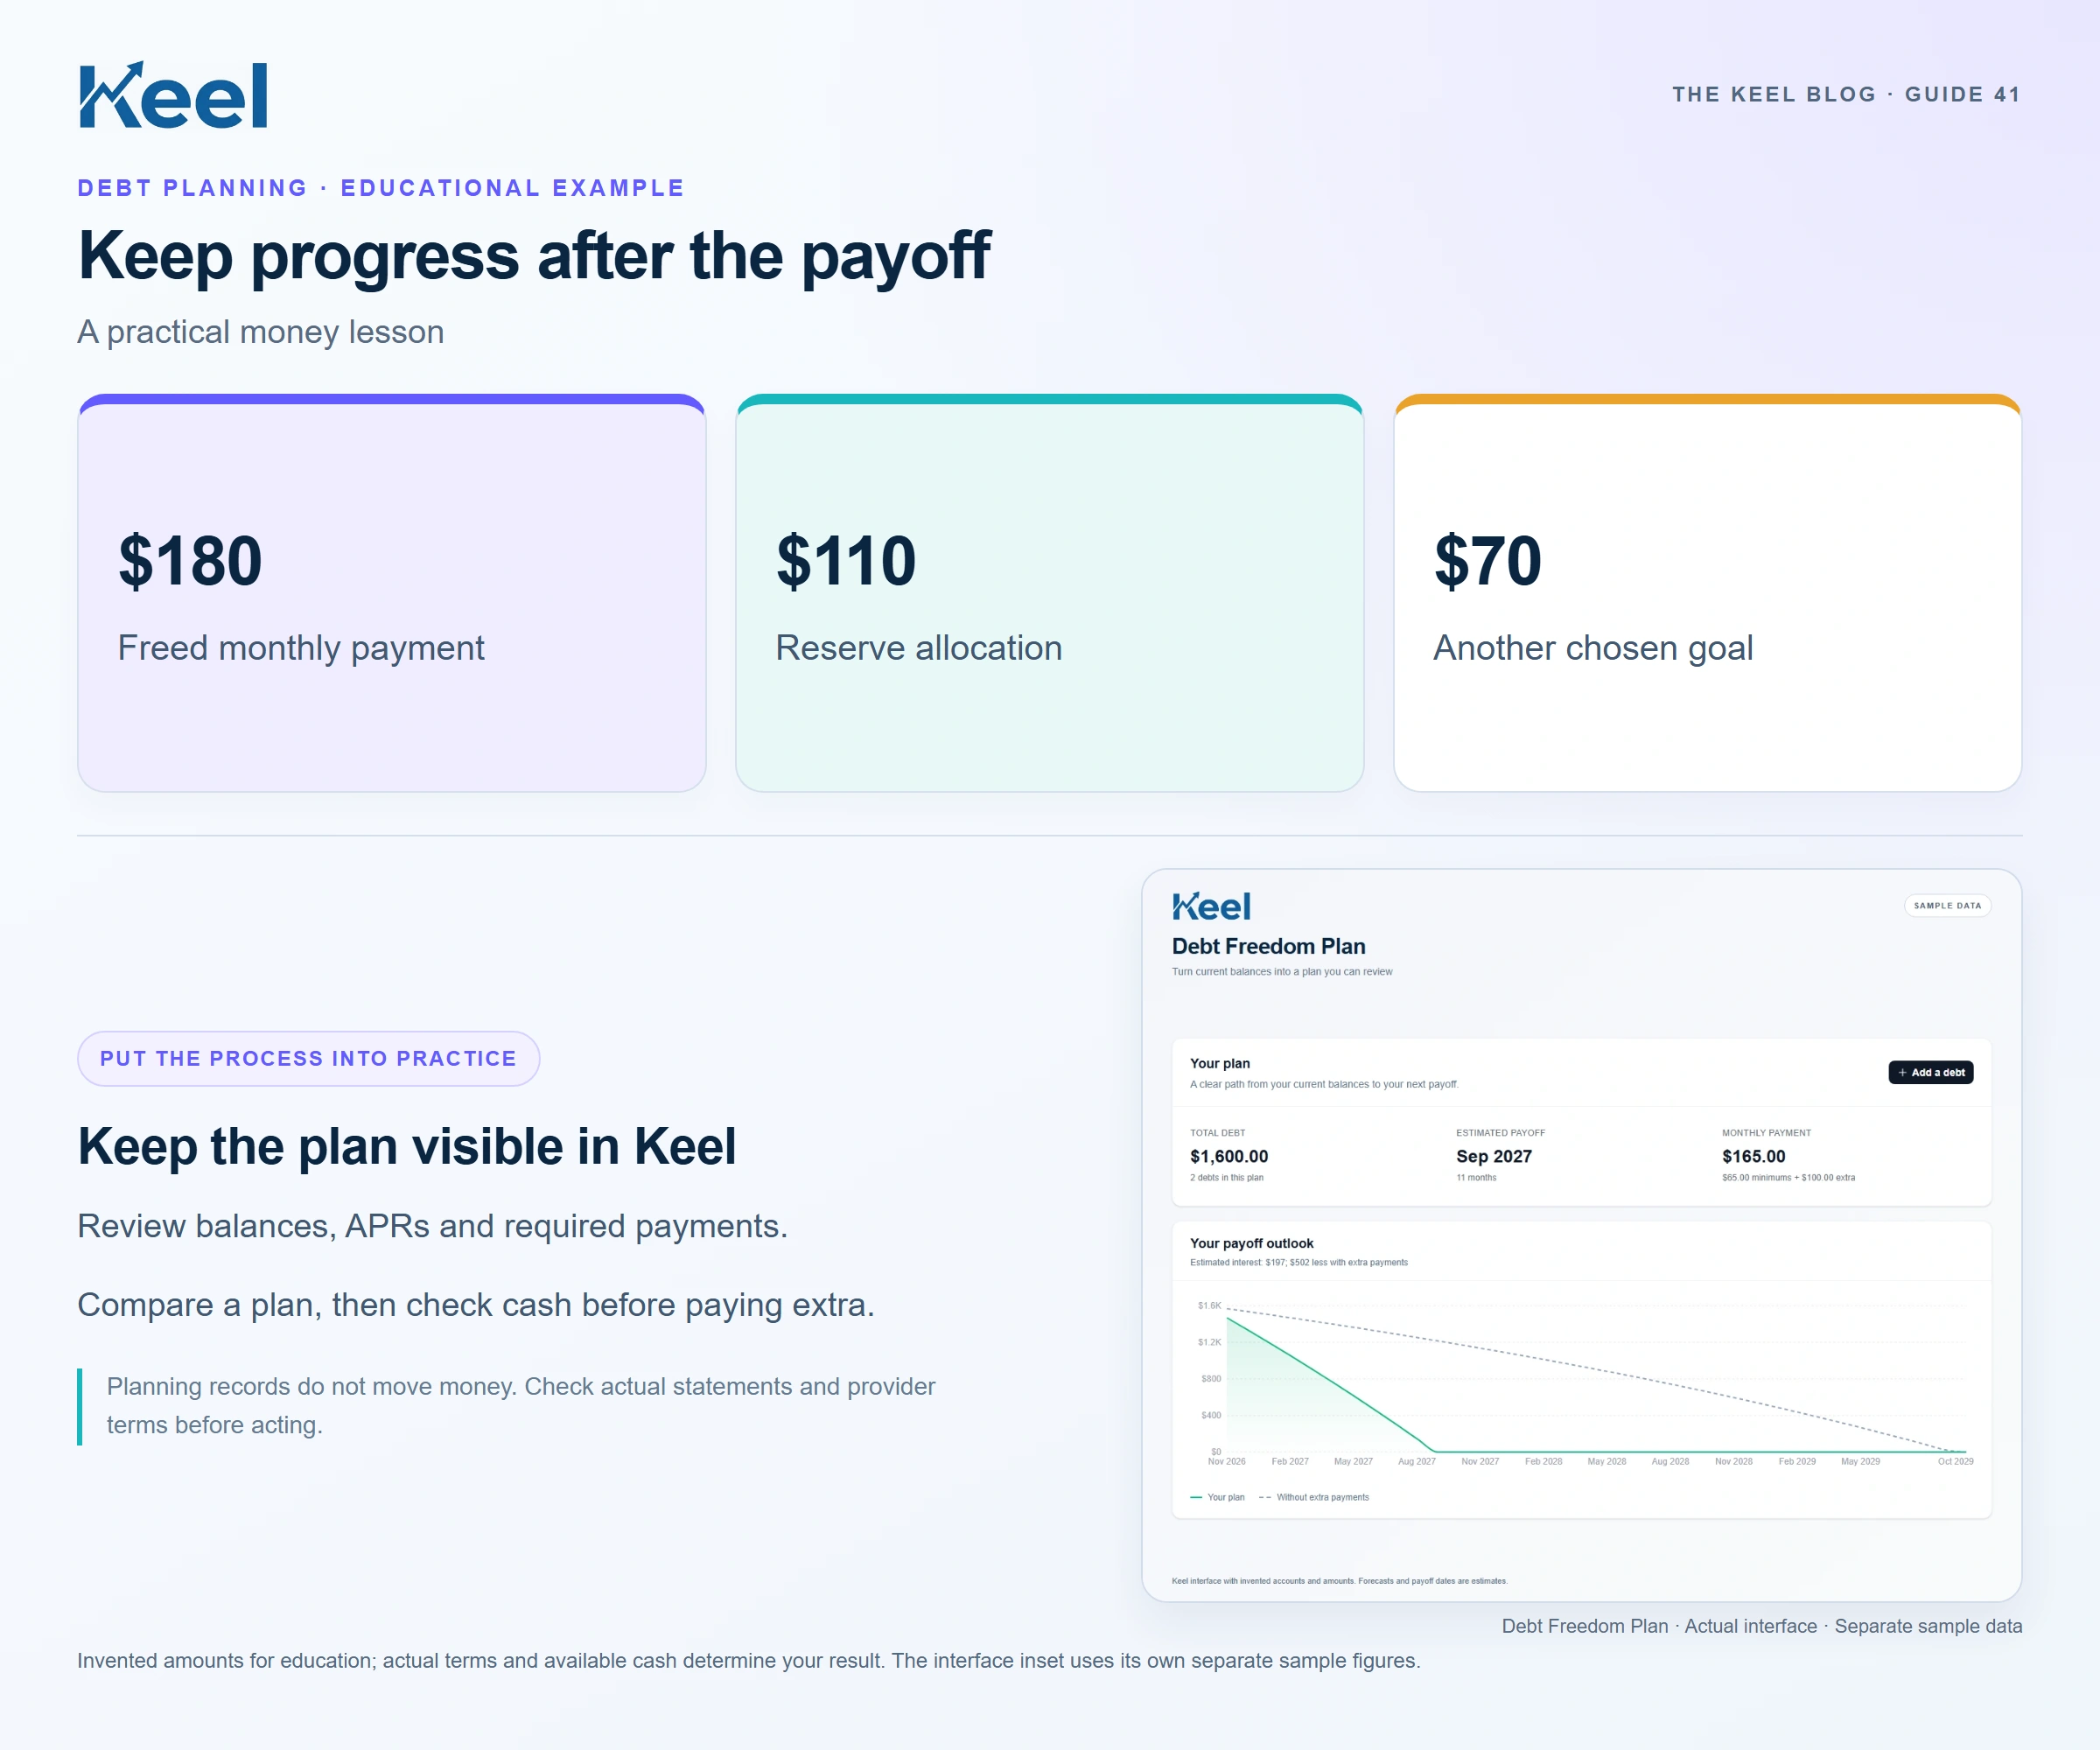
If $180 no longer goes to the cleared debt, one possible choice is $110 to a reserve and $70 to another goal. Six unchanged $110 contributions would add $660 before interest or withdrawals. This is a sample assignment, not a universal split. Check upcoming bills before treating the entire amount as newly available.
| Purpose | Monthly amount |
|---|---|
| Reserve | $110 |
| Other goal | $70 |
| Total redirected | $180 |
Update Keel from confirmed records
Review the debt’s actual balance in Keel and remove obsolete bill planning only after confirming the obligation has ended. Update Savings when money is genuinely set aside. Keel records goals and plans; it does not move the old payment to a new account or certify that a lender has released a lien.
Keep a lighter review habit
Continue checking transactions, annual costs and cash-flow timing. If borrowing again becomes necessary, compare the full commitment rather than only the payment that now seems affordable. Celebrate the completed obligation in a way that fits the budget. The goal is to keep the financial room you created and use it for a chosen purpose.
Footnotes and sources
U.S. consumer education. Sources checked . General education, not an individual financial or legal recommendation.