
Ask Your Card Issuer About a Lower APR
Prepare a focused rate-review conversation, compare the full terms of any offer and update your debt plan only after the issuer confirms the change.
By Keel · Debt planning ·
Free 7-day trial. No card required. Subscribe for $4.99/month to continue; no charge unless you subscribe.
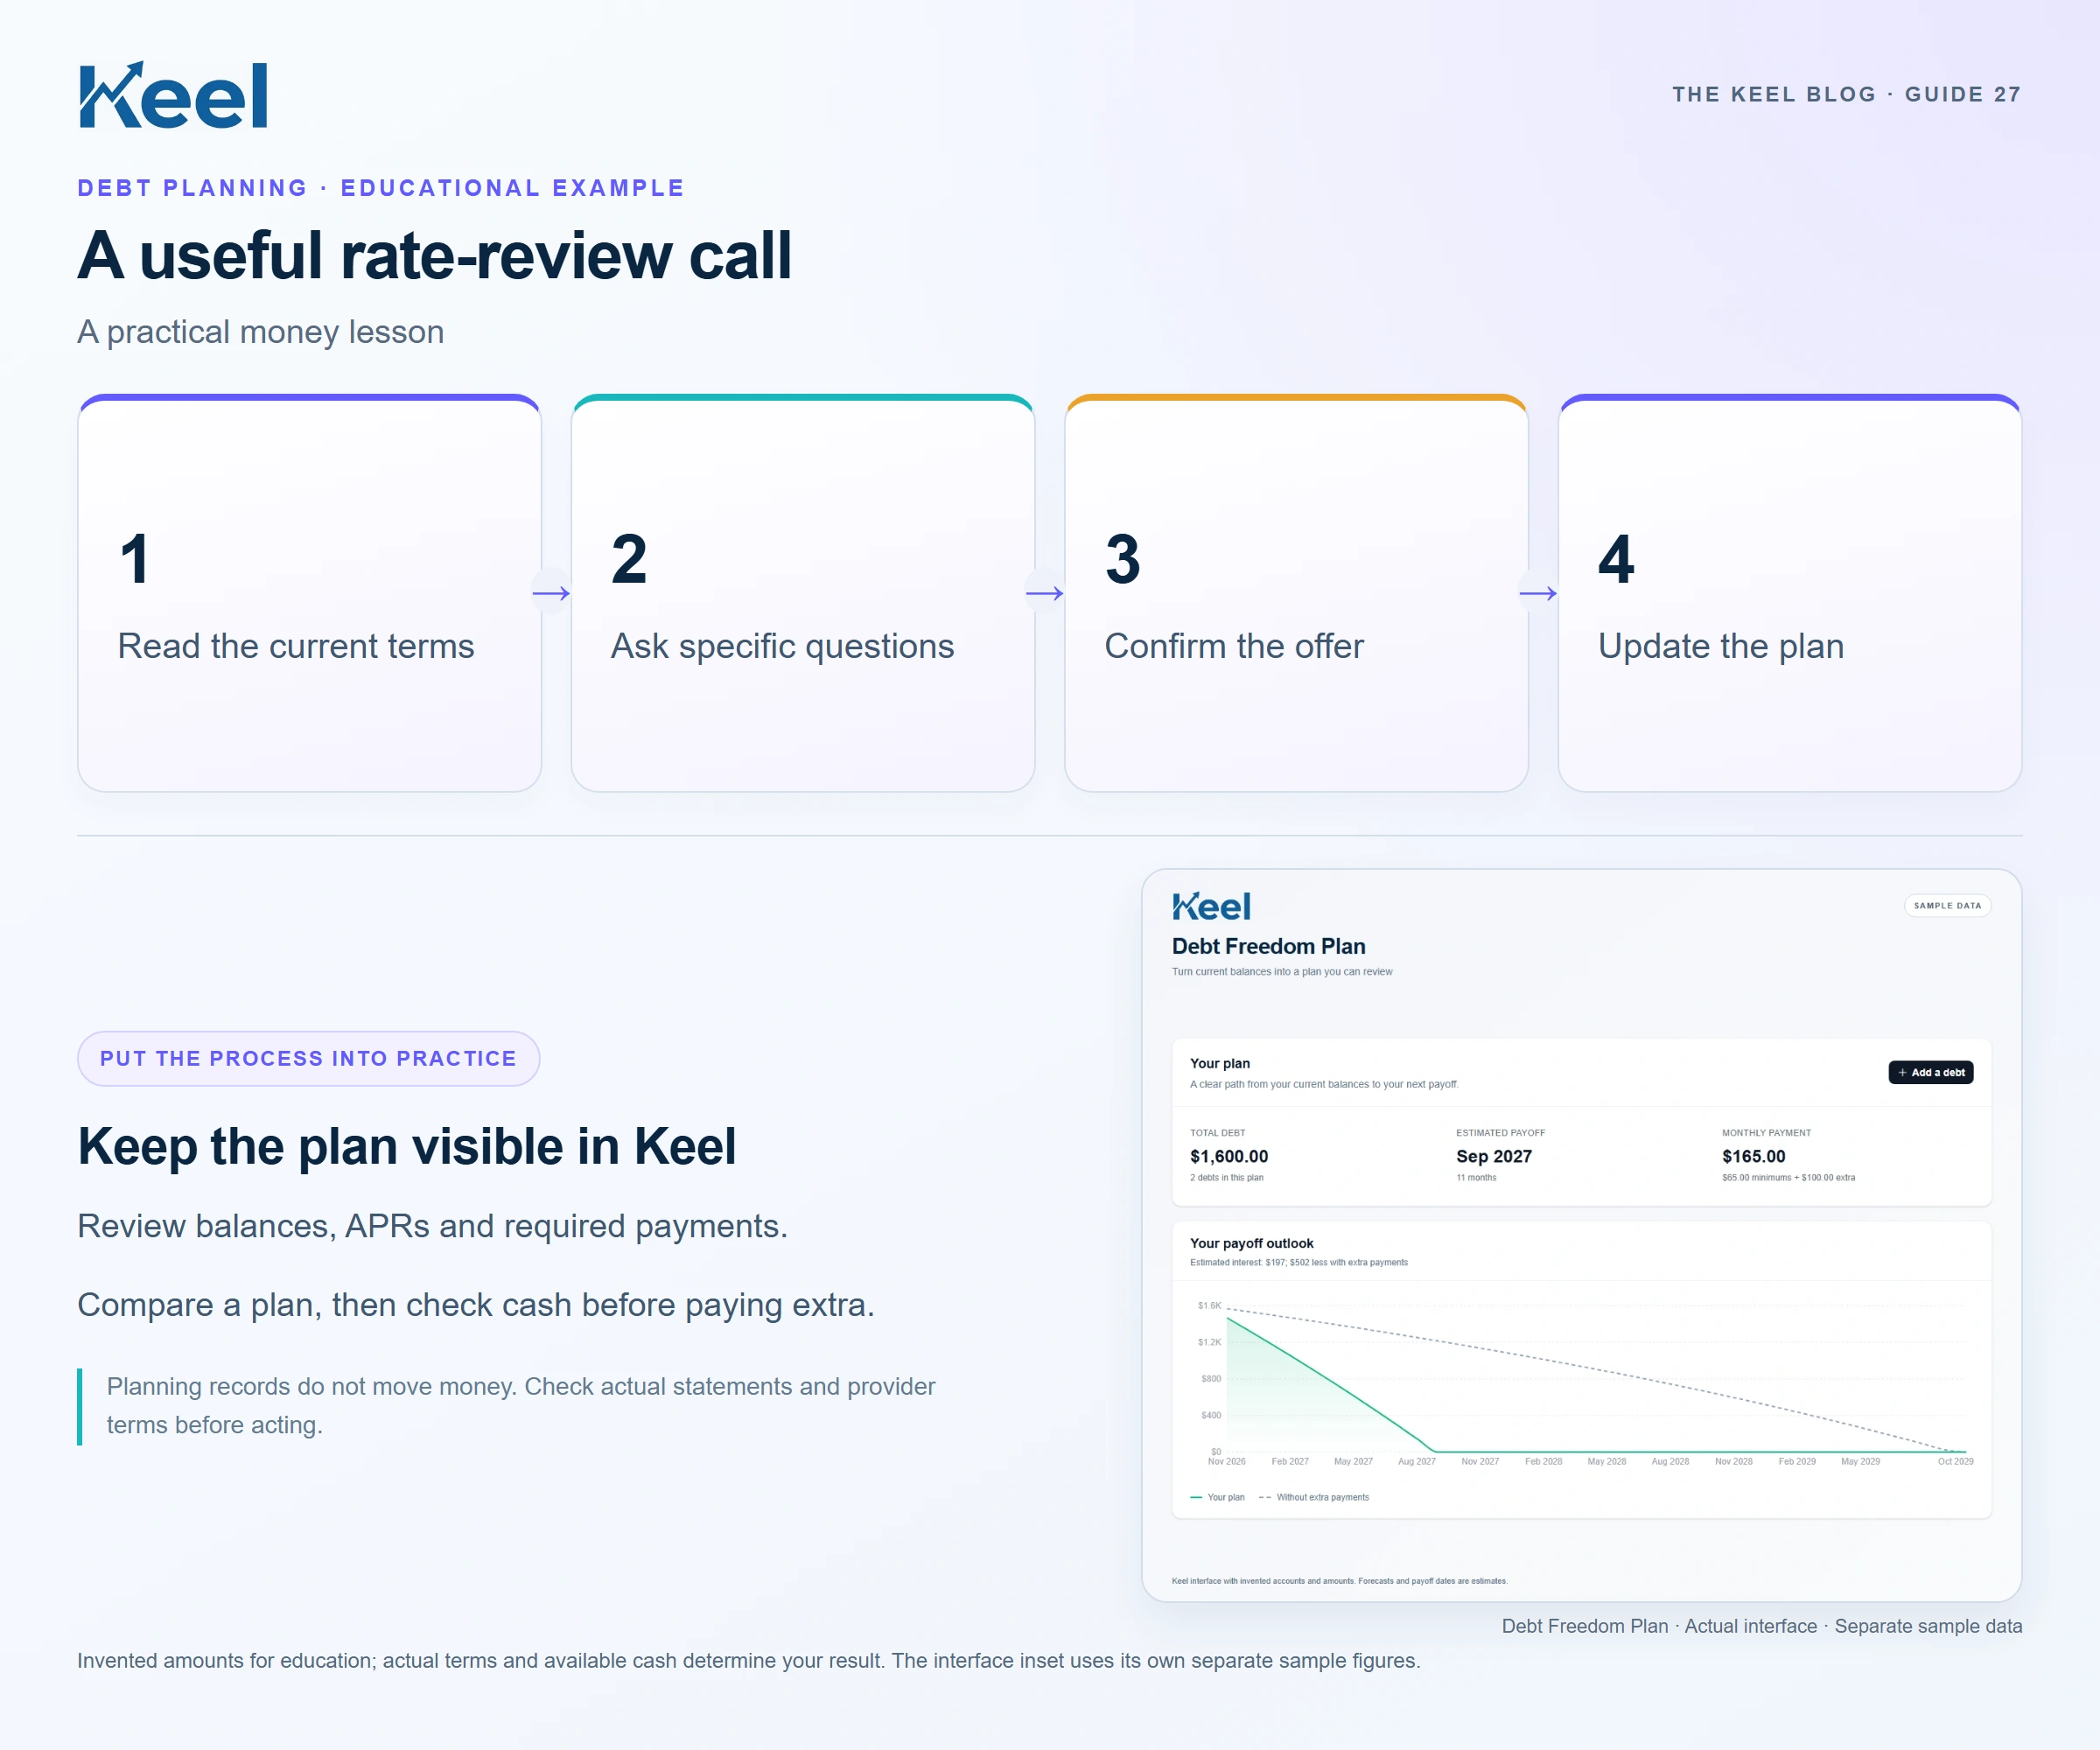
Collect the facts before calling
Find the purchase APR, other balance rates, current balance and payment status on the statement. A single account can contain several rate categories. The CFPB explains why the interest method and applicable APR matter. Identify whether you want a permanent review, a temporary hardship option or an explanation of a rate that changed.[1]
Use a clear request
Call the verified number on the card or issuer website. Ask whether the account qualifies for a lower purchase APR and whether any change is temporary. Ask about fees, required payments, account closure or restrictions and the effective date. If affordability is already a problem, explain the amount you can pay and ask about hardship options directly.[2]
Evaluate the actual response
A lower quoted rate is incomplete without its duration and conditions. An invented offer lasting six months requires another review before month seven. A declined request also provides information: keep the current rate in the plan rather than entering the desired rate. Never miss a required payment because a rate review is pending.
Update Keel after confirmation
In Debt, review the stored APR and any estimated-rate warning. After the issuer confirms new terms, update the relevant input and compare the revised payoff outlook using the same payment amount. Check the forecast before increasing payments. Keel does not call issuers, negotiate APRs or guarantee that its model reproduces every promotional balance category.
Follow up on the first affected statement
Check whether the rate changed as agreed and whether fees or restrictions appeared. Save the issuer’s confirmation outside the planning record. If the offer was temporary, record a personal follow-up date and review the plan before expiry. Rate relief can support repayment, but continuing to add unaffordable purchases can erase that benefit.
Footnotes and sources
U.S. consumer education. Sources checked . General education, not an individual financial or legal recommendation.