
Plan for a Deferred-Interest Deadline
Distinguish deferred interest from a standard zero-percent offer, calculate a deadline target and verify how the issuer allocates payments.
By Keel · Debt planning ·
Free 7-day trial. No card required. Subscribe for $4.99/month to continue; no charge unless you subscribe.
Identify what the promotion actually says
A deferred-interest offer can charge interest dating back to the purchase if the balance is not cleared under its conditions. The CFPB distinguishes this from simply having a zero-percent rate for a period. Read the complete terms, balance covered, expiry and late-payment consequences. Do not infer the arrangement solely from a store’s large zero-interest headline.[1]
Count real payment opportunities
Use the promotion’s actual end date rather than assuming it matches the normal monthly due date. Allow time for processing and correction. A required minimum can be lower than the amount needed to finish before expiry. Ask about payment allocation when the same card has other balances, because sending enough total money does not necessarily clear the intended promotional balance.
Calculate a simple target
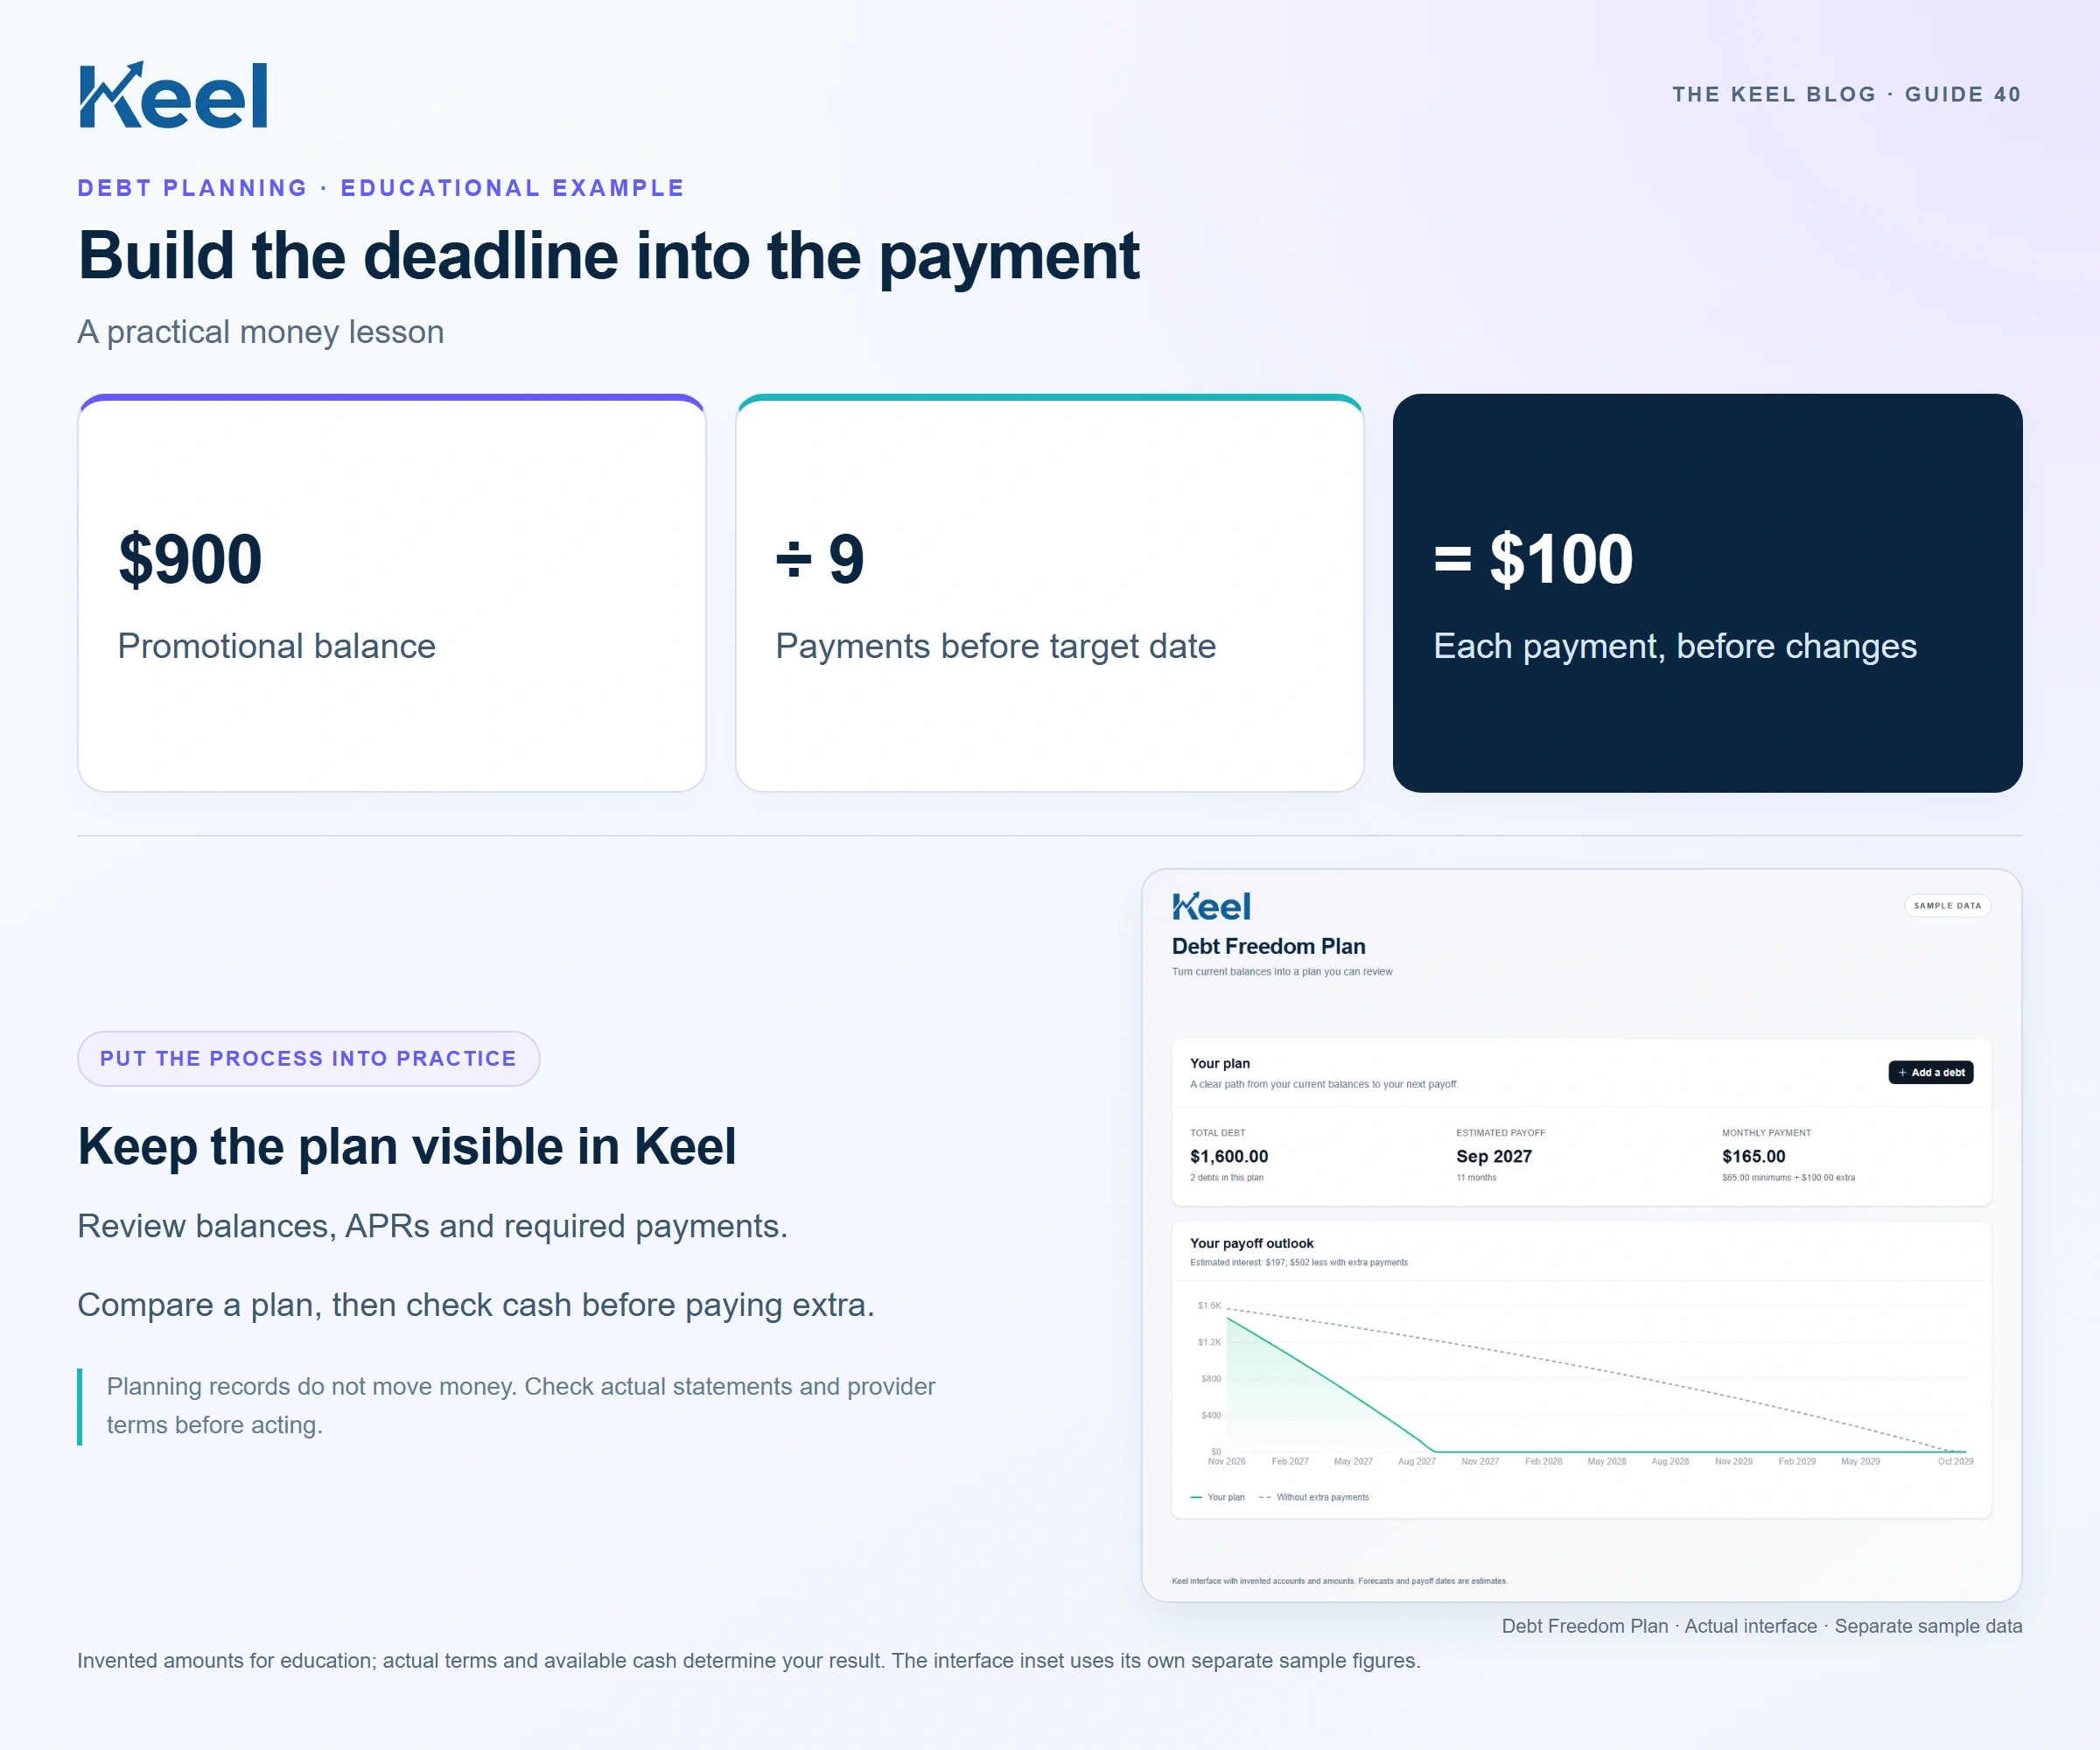
An invented $900 balance with nine equal payments before a chosen early target date requires $100 each time, assuming no new charges or adjustments. If only six payments remain, it requires $150. This illustrates funding capacity, not issuer payment allocation. Verify the promotional balance itself after each payment.
| Payments left | Required per payment |
|---|---|
| 9 | $100 |
| 6 | $150 |
Use Keel without overstating the model
Track the relevant debt balance and required bill date in Keel, and keep the promotional deadline in your own review notes. Inspect cash flow before committing the target payment. Keel’s general payoff estimate does not guarantee the issuer’s promotion-specific result. Preserve provider documentation and confirm whether payment instructions achieve the intended allocation.
Review before the final cycle
Check the remaining promotional amount well before expiry, not on the last possible day. Ask the issuer to resolve discrepancies promptly. Medical financing can also contain promotional conditions, so review assistance options before taking it on. A plan that depends on a last-day transfer with no room for delay needs another check.[2]
Footnotes and sources
U.S. consumer education. Sources checked . General education, not an individual financial or legal recommendation.