
Before You Pay Off an Auto Loan Early
Check prepayment terms, principal-payment instructions and essential cash needs before putting extra money toward a car loan.
By Keel · Debt planning ·
Free 7-day trial. No card required. Subscribe for $4.99/month to continue; no charge unless you subscribe.
Read the prepayment terms
Your contract and state rules determine whether an auto loan can be repaid early without a penalty. The CFPB recommends checking the agreement rather than assuming all loans have identical treatment. An outstanding principal figure may also differ from a final payoff quote that includes accrued interest through a particular date.[1]
Confirm principal-payment instructions
Ask how an extra amount is applied after fees and accrued interest, and whether it changes the next due date. Check the statement after sending it. On a loan where extra principal reduces future interest, that can support repayment, but the actual savings depend on terms and timing. Do not treat an advanced due date as proof that every dollar reached principal.[2]
Protect the costs of keeping the vehicle
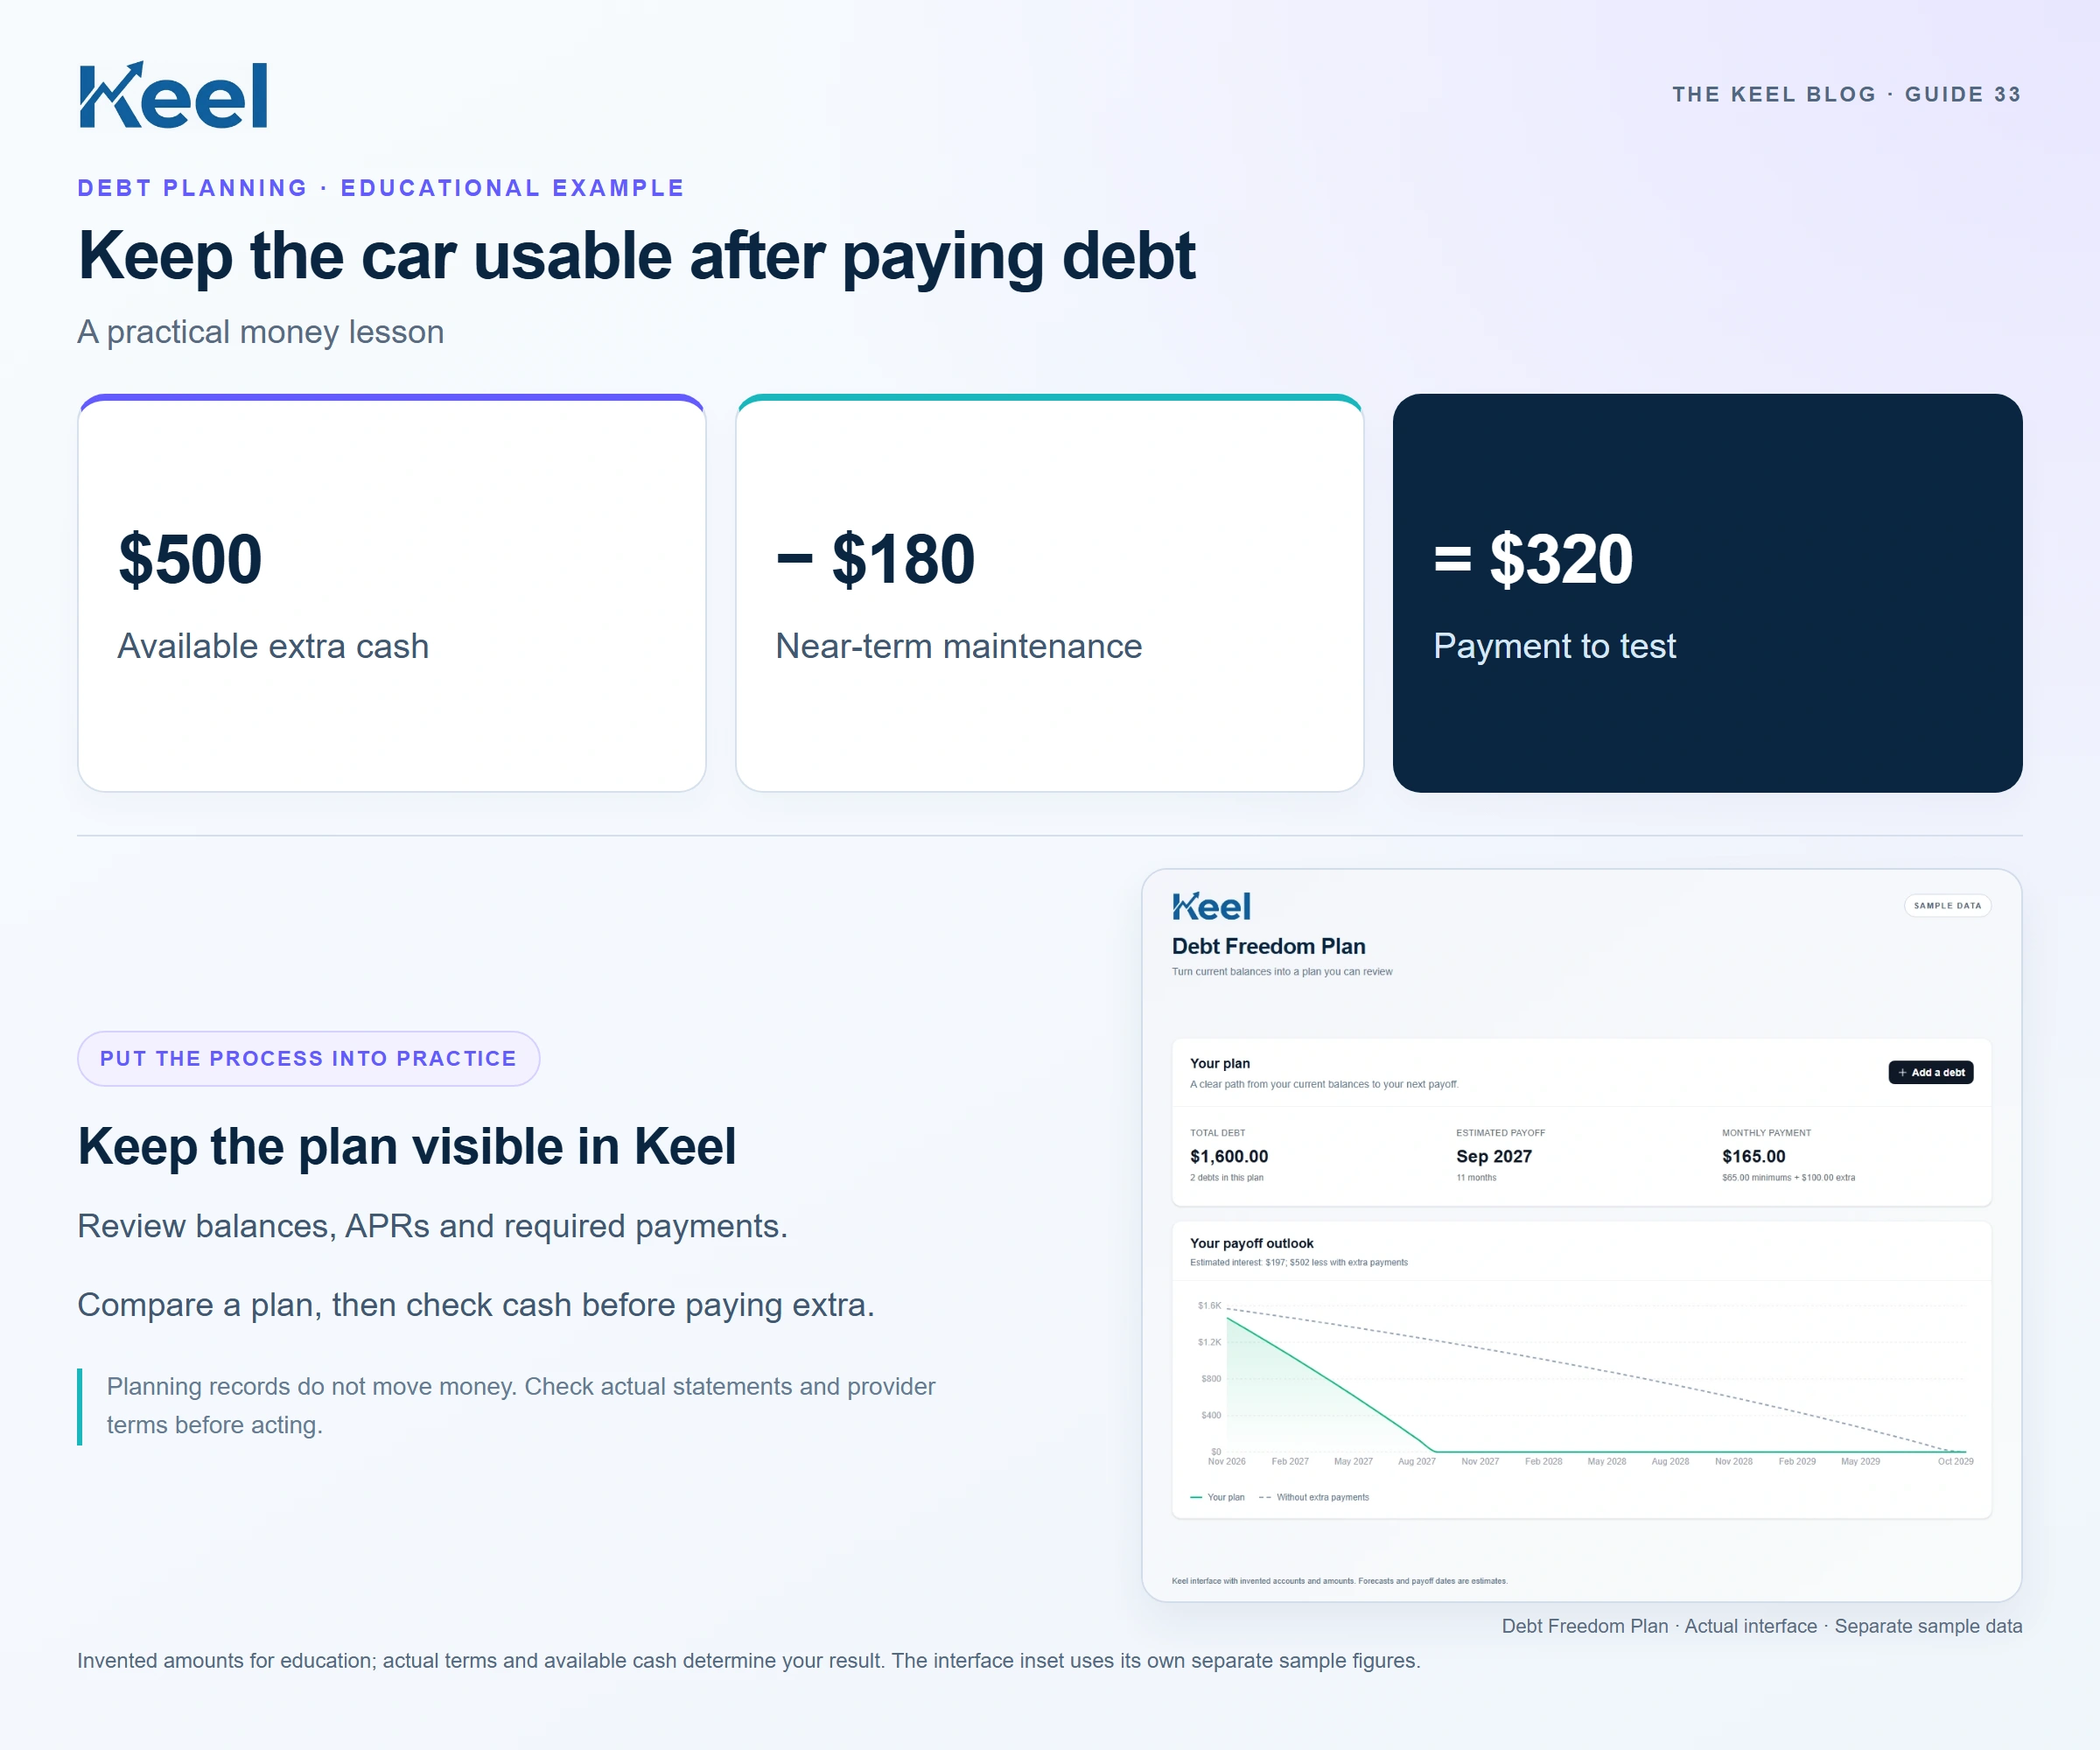
Suppose an invented $500 is available beyond normal obligations, but a $180 maintenance appointment is due before the next paycheck. That leaves $320 to test for an extra loan payment. Insurance, registration and repairs remain expenses even after the loan is cleared. Sending the full $500 may force the maintenance back onto a card.
| Item | Amount |
|---|---|
| Available extra cash | $500 |
| Maintenance due | −$180 |
| Possible extra principal payment | $320 |
Review the tradeoff in Keel
Maintain the lender’s current balance, APR and required payment in Debt, then inspect an extra-payment preview. Use Bills and the cash forecast to keep upcoming vehicle costs visible. Keel does not request title release or obtain an official payoff quote. Those steps remain with the lender and the relevant title process.
Close the loop after the final payment
Confirm a zero balance, ask what documentation follows and verify the status of automatic debits. Check for a final interest adjustment before removing every related reminder. Redirect the old payment deliberately toward another goal while keeping maintenance and insurance funded. A cleared loan improves the plan only when the vehicle’s ongoing costs stay visible.
Footnotes and sources
U.S. consumer education. Sources checked . General education, not an individual financial or legal recommendation.